Yesterday we reported that
in the aftermath of the failure of China's Baoshang Bank (BSB), and its
subsequent seizure by the government - the first takeover of a
commercial bank since the Hainan Development Bank 20 years ago - the
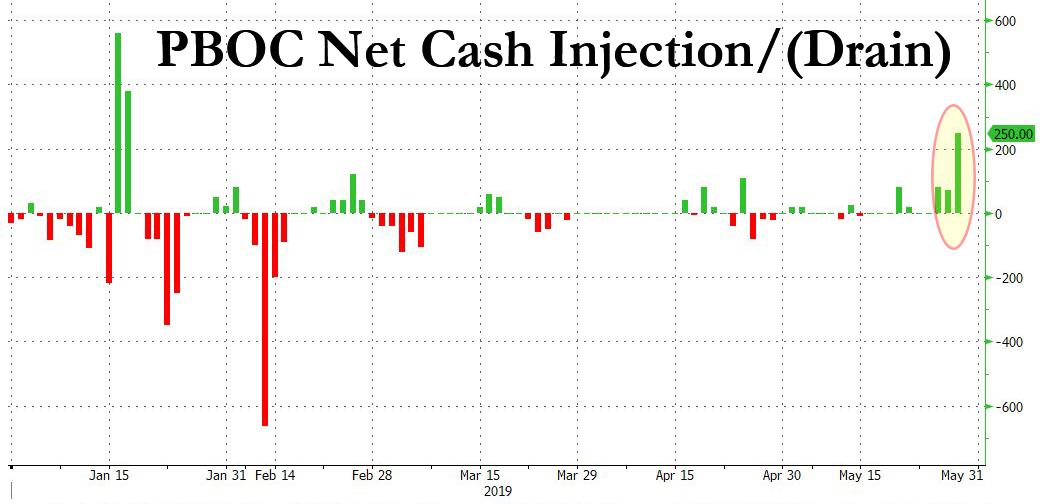
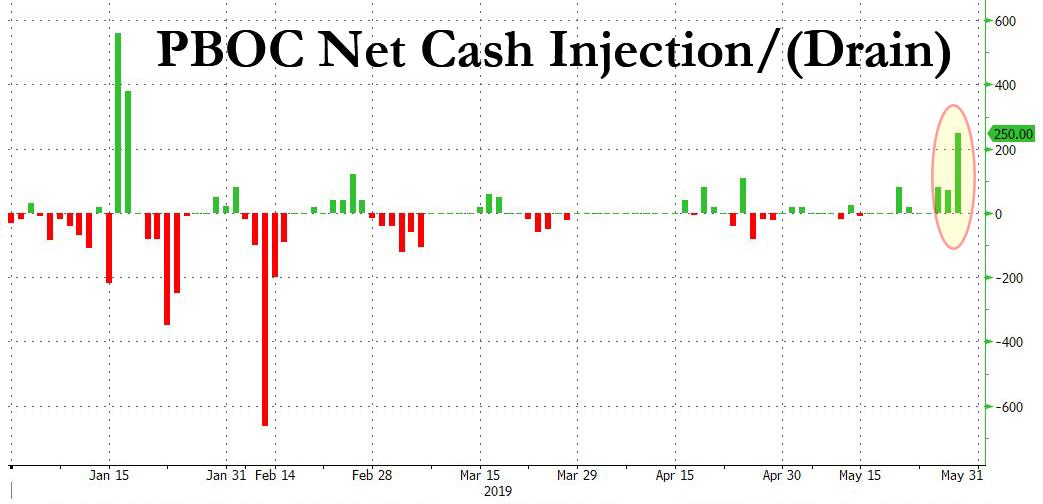
PBOC appeared to panic and injected a whopping 250 billion yuan via an
open-market operation, the largest since January.
昨日ZeroHedgeが記事を書いた、中国のBaoshang Bank(BSB)倒産と国有化の後遺症ーー20年前のHainan Development Bank 海南開発銀行 倒産以来の国有化ーーこれでPBOCはパニック状態になりなんと250B人民元を公開市場操作で注入した、今年1月以来最大のものだった。
And while the bank first failure of a Chinese bank resulted in some
notable turmoil in China's interbank market, where the issuance of
Negotiable Certificates of Deposit was partially frozen as overnight
funding rates spiked, dragging prices of both corporate and sovereign
bonds briefly lower, we warned that "Baoshang is just the tip of the
iceberg."
中国のインターバンク市場が停滞するなかで銀行倒産が生じ、一夜物金利がスパイク急上昇するなかで、Negotiable Certificates of Depositが部分的に凍結された、これが企業債権と中国債をともに短期的に押し下げた、ZeroHedgeはこれを見てこう警告した「Baoshangは氷山の一角に過ぎない」と。
According to UBS analyst Jason Bedford, who in 2017 was the first to
highlight Baoshang’s troubles, there are several other banks that have
“identical leading risk indicators” to Baoshang. Hengfeng Bank, Jinzhou
Bank Co. and Chengdu Rural Commercial Bank all failed to publish their
latest financial statements, have a large portion of their balance
sheets invested in “loan-like investment assets” and are subject to
negative local media coverage.
UBSのアナリストJason Bedfordによると、彼は2017年に最初にBaoshangの抱える問題に注目した人物だ、「Baoshangと同様のリスク指標を持つ銀行がいくつかある」。これらの銀行はまだ最新決算を開示していない、Hengfeng Bank, Jinzhou Bank Co. そしてChengdu Rural Commercial Bankだ、バランスシートのかなりの部分は「ローンに見せかけた投資資産」だ、そして現地のメディアはこの状況をマイナスと捉えて報道している。
To be sure, storm clouds had been gathering above for quite some
time. Here is a quick primer on how BSB was unique, and why it was
especially at risk, courtesy of Barclays.
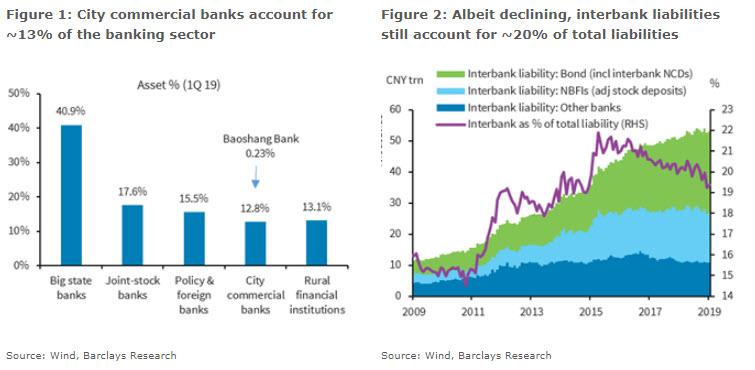
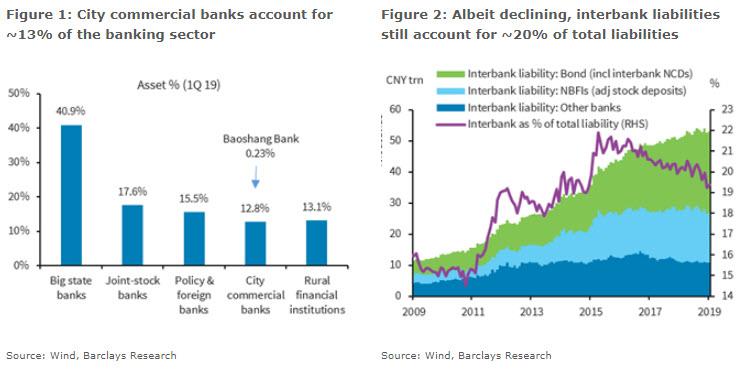
BSB is a city commercial bank (Figure 1), with a AA+ credit rating
from Dagong Credit Rating Group. However, it has faced more problems and
financial difficulties than banks with a similar credit rating. BSB has
not published its annual report since 2016, which to us suggests
significant asset quality stress. Its ratio of 90-day overdue loans to
NPL stood at ~180% in 2016, versus an average of ~110% for similar sized
banks. Meanwhile, its key stakeholder (~30%), Tomorrow Group, has been
under an anti-graft investigation with its founder Xiao Jianhua missing
since 2017.
It has been a notably aggressive player in China’s interbank market, with
~40% of its funding from wholesale sources, compared with a ~25%
average for smaller regional banks, and ~20% for all banks in April 2019 (see Figure 2). As a result, BSB has been hit hard by the deleveraging drive and tightening of the interbank funding channels.
Most of the above was already well-known, at least in the aftermath
of the BSB collapse. What investors are far more curious about is i)
will the failure become systemic, and ii) who will fail next.
Addressing the first question, Barclays analyst Jian Chang writes
that the bank doesn't expect the BSB takeover to cause a systemic crisis
(many would disagree). The reason: the bank's total assets/outstanding
loans/deposits only accounted for 0.23%/0.18%/0.14% of China’s whole
banking system (as of Q3 2017, the latest available data on BSB), and
the PBoC is committed to “keeping eye on the liquidity situation of
medium-to-small banks, and make use of various tools such as OMOs to
ensure reasonably ample liquidity in the system and maintain stability
in the money market rates”.
That said, Barclays admits that the takeover of BSB "highlights
the difficulties and challenges facing some medium-to-small sized banks
arising from China’s deleveraging campaign of the past several years
and a slowing economy." Specifically, during the first phase of
“deleveraging the financial system” (August 2016 - October 2017),
interbank lending, a major funding source facilitating the aggressive
expansion of medium/small banks before, was significantly tightened.
Then as the financial deleveraging extended to the real economy (Nov 17 –
May 18), the resulting rise in corporate delinquency and defaults added
to banks’ credit risks. Then, during the period of policy easing since
the second half of 2018, banks’ asset quality has not been helped by the
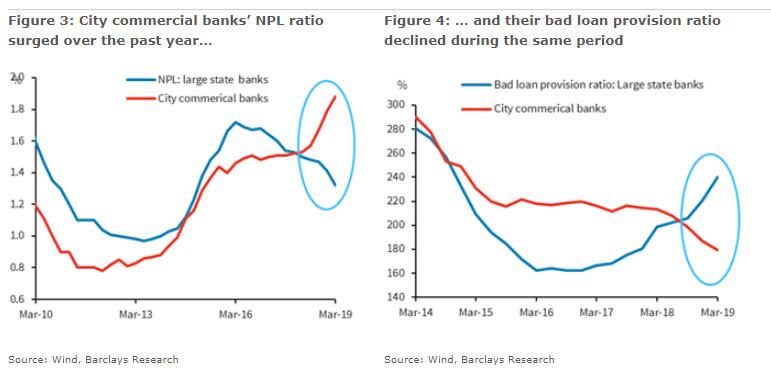
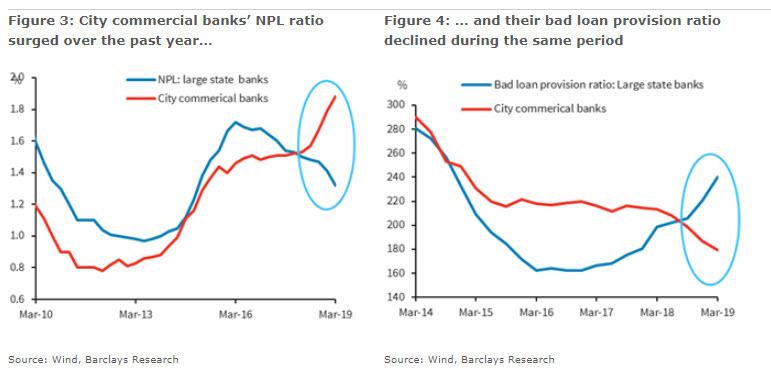
regulator’s push for more SME lending, "as the NPL ratio of
urban commercial banks as a whole rose notably by ~30bp to 1.9% in Q1
19, from 1.6% Q2 18, while their bad-loan provision ratio declined by
30pp to ~180% over the same period (Figures 3-4)." ということで、バークレイ銀行はBSBの国有化をこう解釈している「ここ数年の中国政府の債務削減キャンペーンと景気減速で中小銀行の中には困難が生じている銀行もあることを顕在化せさた」。特に「金融システムの債務削減」の第一フェーズ(2016年8月−2017年10月)においては、かつては中小銀行が積極的に拡大してきた銀行間貸出が大きく引き締められた。その後この金融業界での債務削減が実経済にも拡張された(2018年11月−2018年5月)、結果として企業の返済不能や倒産が銀行の与信リスクを増やした。そして、2018年後半以降は緩和的政策になり、資産の質を監督当局から問われなくなり、小規模銀行の貸出を拡大した、「都市商業銀行の不良債権率は2018Q2の1.6%から30BP増えて2019Q1には1.9%になった、bad loan provision ratio 不良債権引当率(?)は30パーセントポイント減って同じ期間に180%になった(Figure 3-4)。」
As such, Barclays expects more "exits" (read "failures") of smaller
banks or NBFIs (Non-bank financial institutions) either through
takeovers or M&A with bigger parties, most likely with some regional significance (eg.
urban or rural commercial banks. However, in keeping an optimistic
outlook, Barclays does not view a few more bank failures as a systemic
risk, "as the total >130 urban and >1300 rural commercial banks only account for ~10% of the banking sector." というわけで、バークレーは小型銀行やNBFI(ノンバンク金融体、シャドーバンク)においてさらなる「処理」(「損失」)が増えると見ている、処理に際しては大手銀行によるM&Aが伴う。しかしながら、バークレーは楽観的で、さらなる銀行倒産は無いと見ている、「都市銀行は130行を超える中で、1300を超える地方商業銀行の資産規模は銀行セクター全体の10%程度にすぎないからだ」。
Meanwhile, the analyst notes the regulators’ efforts to help banks
replenish their capital through various channels (eg. the recently
introduced perpetual bonds which are a form of quasi QE) as "indicated by the government’s attempts to prevent systemic risks from materializing before they become too great to contain."
Furthermore, the official remarks (listed below) suggest that, even if some FIs are allowed to "experiment"
with bankruptcy, this would only go forward in a controlled and
manageable manner (ie. mainly through mergers and restructuring) to
ensure the government’s bottom line of no systemic risks being created.
Below is a list of selected comments by a Chinese official, in this
case Xiao Yuanqi, the Chief Risk Officer of the CBIRC, in February 2019,
which help understand the regulators’ thinking on smaller FIs, NPL risk
exposure, and planned resolutions:
He said that regulators will continue encouraging smaller and
private players to join the market to expand access to credit for SMEs,
meanwhile they will also work out measures to contain risks associated
with smaller financial institutions (FIs).
While some institutions will be allowed to experiment with
bankruptcy, regulators will mainly use mergers and restructuring to
defuse risks and force unqualified players out of the market.
The authorities will also encourage lenders to step up efforts to
offload their non-performing loans (NPLs). The banking sector has
disposed of CNY3.48trn of bad loans over the past two years, according
to CBIRC data, but commercial banks still have CNY2trn of NPLs on their
balance sheets.
Improving the supply of financing will involve shifting
“inefficient” credit from industries suffering from overcapacity to
areas with greater needs, such as SMEs in innovative and strategic
sectors. Poorly performing companies with little prospect of improvement
will be guided to exit the market through reorganization or bankruptcy.
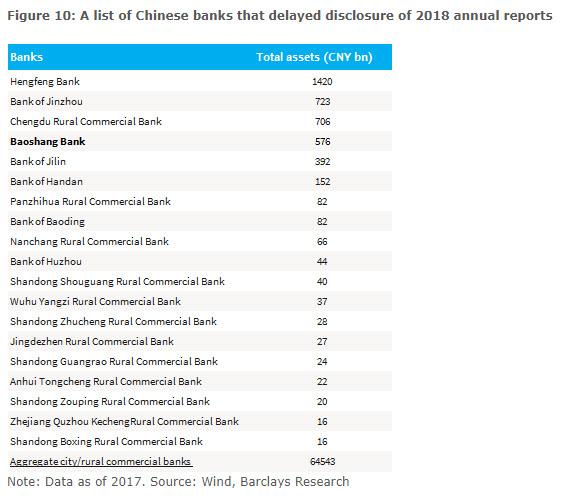
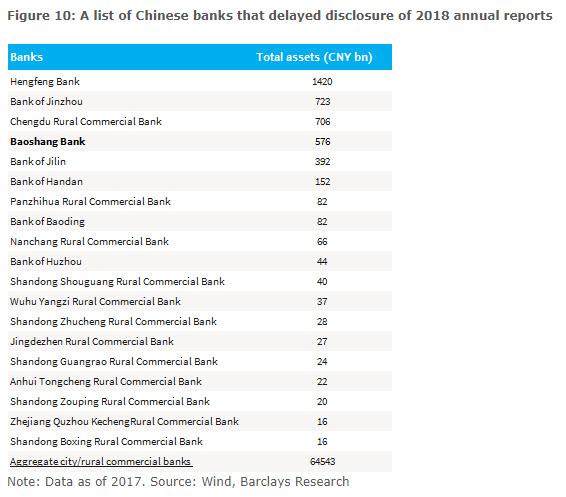
Finally, for those curious which banks are most likely to follow
in Baoshang's footsteps, and fail next, Barclays has compiled a list of regional banks that have delayed publishing 2018 reports, the biggest red flag suggesting an upcoming solvency "event."
Amazonで買物をしてContrarianJを応援しよう この長文記事をRay Dalioが発表し、ゴールドは$1400から$1420へと急騰しました。GLD保持高に変化はないのでたぶん先物ポジションが進んでいます。 Ray Dalio Warns A "New Paradigm" Is Coming: "Buy Gold, Sell Stocks" by Tyler Durden Wed, 07/17/2019 - 14:44 Authored by Ray Dalio via LinkedIn, One of my investment principles is: 私の投資原則はこういうものだ: Identify the paradigm you’re in, examine if and how it is unsustainable, and visualize how the paradigm shift will transpire when that which is unsustainable stops. 現在のパラダイムを認識し、それがどの程度持続可能かどうか判断する、そしてパラダイムシフトがどのように起きるか、そしてその着地点を思い描く。 Over my roughly 50 years of being a global macro investor, I have observed there to be relatively long of periods (about 10 years) in which the markets and market relationships operate in a certain way (which I call “paradig...
Amazonで買物をしてContrarianJを応援しよう Silver Outperforming Gold 2 Adam Hamilton July 26, 2019 3232 Words Silver has blasted higher in the last couple weeks, far outperforming gold. This is certainly noteworthy, as silver has stunk up the precious-metals joint for years. This deeply-out-of-favor metal may be embarking on a sea-change sentiment shift, finally returning to amplifying gold’s upside. Silver is not only radically undervalued relative to gold, but investors are aggressively buying. Silver’s upside potential is massive. ここ2週シルバーは急騰した、ゴールドを遥かに凌ぐものだ。これは注目すべきことだ、もう何年もシルバーはひどいものだった。この極端に嫌われた金属が大きく心理を買えている、とうとうゴールド上昇を増幅するに至った。シルバーは対ゴールドで極端に過小評価されているだけでなく、投資家は積極的に買い進んでいる。シルバーの潜在上昇力は巨大なものだ。 Silver’s performance in recent years has been brutally bad, repelling all but the most fanatical contrarians. Historically silver prices have been mostly ...
The US Consumer Just Hit A Brick Wall: Here's Why In 15 Charts by Tyler Durden Tue, 03/05/2019 - 17:05 When it comes to the growth dynamo behind the global economy, nobody can match the US consumer - not even China: accounting for trillions in annual spending, the US consumer, who represents roughly 70% of US GDP, is also responsible for roughly 17% of global GDP, slightly ahead of the entire country of China. 世界経済の成長エンジンを議論する時、米国消費以上のものはないーー中国ではない:年間トリリオンドルを米国消費者は使っている、これが米国GDPの70%、そして世界GDPの17%を占める、中国全GDPよりも大きい。 However, as recent economic data has shown, the future of the US consumer is suddenly looking ominously cloudy, for two big reasons: rising interest rates, which as Deutsche Bank notes are "beginning to bite" as observed in the number of working hours in sector selling big ticket items... しかしながら最近の経済デ...
米国はよく理解してませんが、日本の場合では量的緩和で日銀が国債買い上げした資金は日銀当座預金にそのままです、市中には流れていません。でもNHKのニュース等では「ジャブジャブ」という表現をアナウンサーが使い、さらに丁寧に水道の蛇口からお金が吐き出される画像まで示してくれます。これって心理効果が大きいですよね。量的緩和とは何かを7時のニュースや新聞でこれ以上丁寧に解説するのはそう簡単ではありません。一般の人も株式をやっている人も「イメージ」で捉える以上はそう簡単にできません。多くの人は量的緩和とはなにか、を理解していないと私は想像しています。 ただし、国債を買い上げるので長期金利が低下し住宅ローン金利等が下がったのは確実な効果です。一方で長短金利差が少なくなると銀行のビジネスモデルが成り立たなくなりますが。 This Is The One Chart Every Trader Should Have "Taped To Their Screen" by Tyler Durden Sat, 01/19/2019 - 18:55 After a year of tapering, the Fed’s balance sheet finally captured the market’s attention during the last three months of 2018. 一年間のテーパリング後、FEDバランスシートがとうとう市場の注目をあびることになった、2018年の最後の3ヶ月だ。 By the start of the fourth quarter, the Fed had finished raising the caps on monthly roll-off of its balance sheet to the full $50bn per month (peaking at $30bn USTs, $20bn MBS...