In
at least one important way, President Trump's decision to browbeat the
Fed into pausing its program of interest-rate hikes is paying off bigly
for America's most vulnerable corporate borrowers.
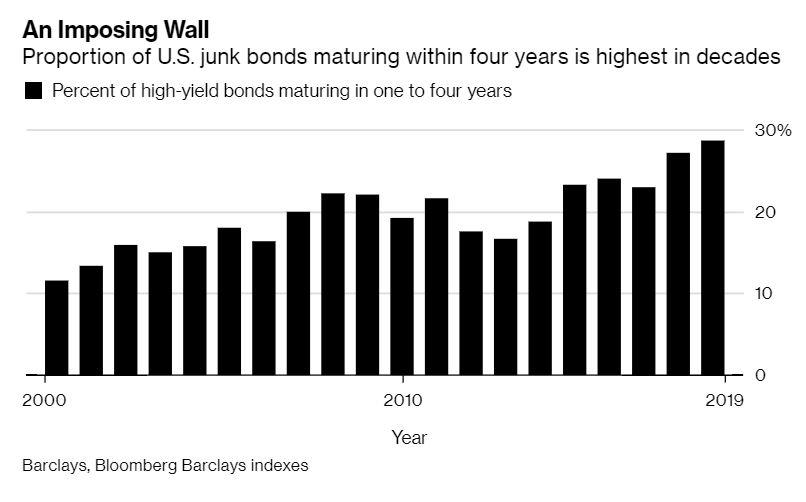
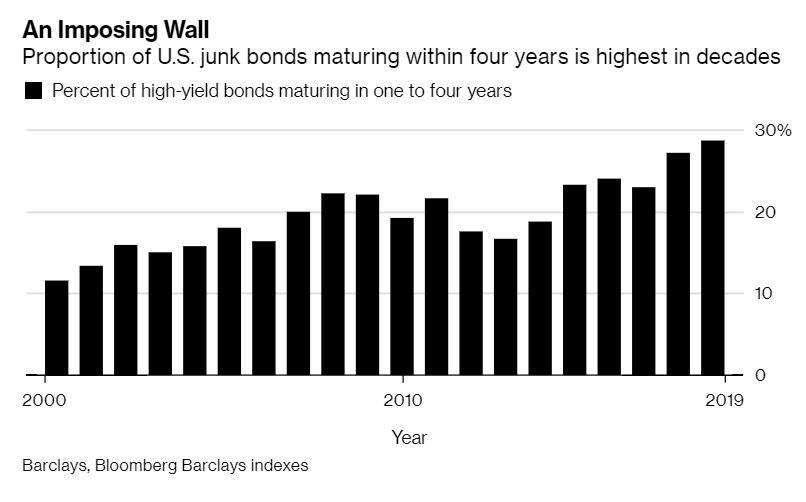
The Fed's decision to 'pause' interest rate hikes comes as nearly
one-third of the entire $1.2 trillion US high-yield market is slated for
maturity over the next four years. That's a record proportion,
according to a team of strategists at Barclays led by Bradley Rogoff,
and compares with a post-2000 average of just 20%. And after the
historic market 'freeze' late last year where not a single high-yield
bond was issued, corporate America has apparently got the message: Now
is the time to strike while the iron is hot. The more speculative-grade the rating, the more important it is for companies to act now to refinance that debt. $1.2Tにもなる米国高金利債権の1/3が今後4年で満期を迎えようとするなかで、FEDが金利引き上げを「中断」することを決めた。Bradley RogoffをリーダーとするBarclaysのストラテジストによると、この割合はとても大きなもので、比較として示すと、2000以降での平均満期割合はわずか20%にすぎなかった。そして昨年遅くに歴史的なこの市場の「凍結」が生じ、まったく高金利債権は発行されなかった、米国全体が明らかにこういうメッセージを発している:今こそ、鉄は熱いうちに打て、ということだ。周囲で投機的企業格付が増えるほどに、多くの企業にとってはいまいそいで債務の借り換えをすることがさらに大切になる。
Though many companies have years to plan on refinancing (almost none
will pay off their debt tabs entirely), many are choosing to refinance
now, while rates are low, and demand for higher-yielding debt is high.
Junk bonds tanked last week as markets shunned risky assets, but this
didn't dampen buyers' appetite: Last week was the biggest week for
issuance in nearly two years, with junk issuers selling $12 billion. So
far this year, more than $80 billion of bonds that listed refinancing in
the prospectus have been issued. That has accounted for more than 70%
of the issuance so far this year, according to Bloomberg.
And while credit analysts at some of the bigger fund managers insist
that this is 'healthy', they seem to have neglected the fact that the
president has effectively given corporations a green light to continue
on their debt binge by effectively putting off their day of reckoning
until the Democrats take back control of the White House.
"Companies are extending maturities out, and that’s healthy," said
Scott Roberts, head of high-yield debt at Invesco Ltd. Refinancing is a
better use of debt than buying back shares, he added. "I’ve seen frothy
before and this is not it."
"I feel good about this high-yield market and we are trying to push issuers to take advantage of it,"
said Richard Zogheb, global head of debt capital markets at Citigroup
Inc. "Investors are so excited now that the underlying rate environment
is more dovish, and that’s really good news for high-yield borrowers."
Companies that backed out of their issuance plans late last year
during the sudden market drought are beginning to realize that 'market
conditions' probably aren't going to get much better than they are now.
"We had half a dozen companies that were planning to go as early as
nine or 10 months ago, then the market started weakening and we never
got to the point where we could do those deals," said John Gregory, head
of leveraged-finance syndicate at Wells Fargo & Co., referring to
when junk bond prices fell late last year. "Now we’re finally getting to that point."
What's more, floating-rate leveraged loans have become less
attractive thanks to the Fed's capitulation, creating something of a
perfect storm for the junk-bond market, which is great for heavily
indebted companies hoping to lock in the lowest possible interest rate. 更に言うと、変動金利レバレッジドローンはそれほど魅力的にならなくなった、FEDが罠に陥ったためだ、これがジャンクボンド市場に何らかの嵐を引き起こしつつある、債務過多の企業にとって最低金利を得ることを期待している。
"I can’t remember when $5 billion worth of deals came in one day," said Matt Eagan, a portfolio manager at Loomis Sayles & Co.
"The market is generally wide open for issuers," said Jenny Lee,
co-head of leveraged loan and high-yield capital markets at JPMorgan
Chase & Co. "We’re advising issuer clients to look harder at doing
high-yield bonds."
Even if borrowers truly can't afford it, the longer they can delay
their day of reckoning, the greater the chance that the Fed takes care
of their obligations for them when the central bank inevitably pivots to
buying corporate debt - as former Fed Chairwoman Janet Yellen recently
suggested - during QE4.
Amazonで買物をしてContrarianJを応援しよう 記事を紹介しようと訳を入れている間にFOMCが過ぎてしまいタイミングを逸してしまいました、前半は読み飛ばしてください。後半部分に関して、日本では一般会計と特別会計が別れていて政府財政がわかりにくいですが、米国は分離されておらず年金会計がより鮮明になります。$70Tって邦貨でいうと約7000兆円ですからね。 Whistling Past The $70 Trillion Debt Graveyard 07-26-19 Written by Lance Roberts | Jul, 27, 2019 Last week, we discussed the setup for a near-term mean reversion because of the massive extension above the long-term mean. To wit: 先週には、私どもは短期的な平均回帰のし掛けが出来上がっていることを議論した、というのも現在長期的な平均から極端に乖離しているからだ。見てみよう: “There is also just the simple issue that markets are very extended above their long-term trends, as shown in the chart below. A geopolitical event, a shift in expectations, or an acceleration in economic weakness in the U.S. could spark a mean-reverting event which would be quite the norm of what we have seen in recent years.” 「とてもかんたんなことだが、市場は長期的なトレンドからあまりに極端に上方乖離している、それは下のチャートを見れば明らかだ。地政学的出来事、期待値の変化、もしくは米国経済の弱さが加速するなら、平均回帰を引き起こすだろう、それは過去数年でみた典型的な相場の動きだ。」 This analysis is ...
Amazonで買物をしてContrarianJを応援しよう この長文記事をRay Dalioが発表し、ゴールドは$1400から$1420へと急騰しました。GLD保持高に変化はないのでたぶん先物ポジションが進んでいます。 Ray Dalio Warns A "New Paradigm" Is Coming: "Buy Gold, Sell Stocks" by Tyler Durden Wed, 07/17/2019 - 14:44 Authored by Ray Dalio via LinkedIn, One of my investment principles is: 私の投資原則はこういうものだ: Identify the paradigm you’re in, examine if and how it is unsustainable, and visualize how the paradigm shift will transpire when that which is unsustainable stops. 現在のパラダイムを認識し、それがどの程度持続可能かどうか判断する、そしてパラダイムシフトがどのように起きるか、そしてその着地点を思い描く。 Over my roughly 50 years of being a global macro investor, I have observed there to be relatively long of periods (about 10 years) in which the markets and market relationships operate in a certain way (which I call “paradig...
Productivity: What It Is & Why It Matters Written by Michael Lebowitz | Jan, 16, 2019 The Kansas City Federal Reserve posted the Twitter comment and graph below highlighting a very important economic theme. Although productivity is a basic building block of economic analysis, it is one that few economists and even fewer investors seem to appreciate. Kansas 市FEDがツイッターにコメントを投稿した、そのグラフを下に示す、とても重要な経済テーマだ。経済分析においては生産性というのはとても重要な要素だが、ほとんどのエコノミストがこの件に言及しない、投資家は更にこのことを忘れ去っている。 The Kansas City Fed’s tweet is 100% correct in that wages are stagnating in large part due to low productivity growth. As the second chart shows, it is not only wages. The post financial-crisis economic expansion, despite being within months of a record for duration, is by far the weakest since WWII. Kansas City FEDのツイートは100%正しい、給与が停滞している原因の主要因は生産性成長が低いからだ。二番目のチャートを見ても判るように、成長鈍化は給与だけではない。あの金融危機後の経済拡大は、第二次世界大戦後で記録的長期の拡大期間だが、とても弱い拡大だ。 Productivity growth over the last 350+ years is ...
米国はよく理解してませんが、日本の場合では量的緩和で日銀が国債買い上げした資金は日銀当座預金にそのままです、市中には流れていません。でもNHKのニュース等では「ジャブジャブ」という表現をアナウンサーが使い、さらに丁寧に水道の蛇口からお金が吐き出される画像まで示してくれます。これって心理効果が大きいですよね。量的緩和とは何かを7時のニュースや新聞でこれ以上丁寧に解説するのはそう簡単ではありません。一般の人も株式をやっている人も「イメージ」で捉える以上はそう簡単にできません。多くの人は量的緩和とはなにか、を理解していないと私は想像しています。 ただし、国債を買い上げるので長期金利が低下し住宅ローン金利等が下がったのは確実な効果です。一方で長短金利差が少なくなると銀行のビジネスモデルが成り立たなくなりますが。 This Is The One Chart Every Trader Should Have "Taped To Their Screen" by Tyler Durden Sat, 01/19/2019 - 18:55 After a year of tapering, the Fed’s balance sheet finally captured the market’s attention during the last three months of 2018. 一年間のテーパリング後、FEDバランスシートがとうとう市場の注目をあびることになった、2018年の最後の3ヶ月だ。 By the start of the fourth quarter, the Fed had finished raising the caps on monthly roll-off of its balance sheet to the full $50bn per month (peaking at $30bn USTs, $20bn MBS...