Deutsche Bank
strategists Jim Reid and Craig Nicol wrote a report this week that
echos what I and other Austrian School economists been saying for many
years: actions taken by governments and central banks to extend
business cycles and prevent recessions lead to even more severe
recessions in the end.MarketWatch reports –
ドイツ銀行のストラテジスト Jim Reid とCraig Nicolが今週報告書を書いた、その内容は私や他のオーストリア学派経済学者が長年警鐘を告げていたものと同様だ:政府や中央銀行がビジネスサイクルを引き延ばし景気後退を回避しようとするが、これが結局もっと深刻な景気後退を引き起こす。
MarketWatchの報告ーー
The 10-year old economic
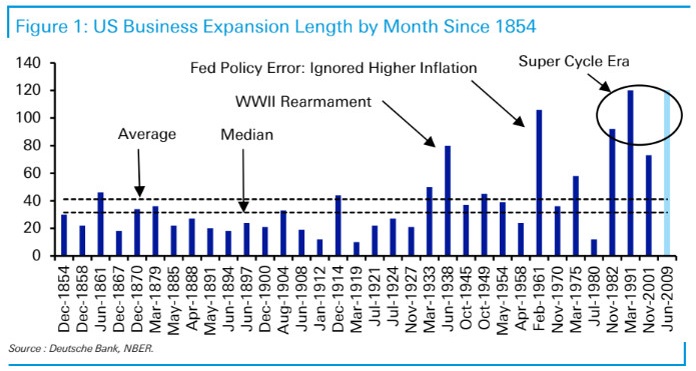
expansion will set a record next month by becoming the longest ever.
Great news, right? Maybe not, say strategists at Deutsche Bank.
Prolonged
expansions have become the norm since the early 1970s, when the tight
link between the dollar and gold was broken. The last four expansions
are among the six longest in U.S. history .
Why so? Freed from the
constraints of gold-backed currency, governments and central banks have
grown far more aggressive in combating downturns. They’ve boosted
spending, slashed interest rates or taken other unorthodox steps to
stimulate the economy.
“This
policy flexibility and longer business cycle era has led to higher
structural budget deficits, higher private sector and government debt,
lower and lower interest rates, negative real yields, inflated financial
asset valuations, much lower defaults (ultra cheap funding), less
creative destruction, and a financial system that is prone to crises,’ they wrote in a lengthy report.
“In
fact we’ve created an environment where recessions are a global
systemic risk. As such, the authorities have become even more encouraged
to prevent them, which could lead to skewed preferences in
policymaking,” they said.“So we think cycles continue
to be extended at a cost of increasing debt, more money printing, and
increasing financial market instability.”
As I have explained
in the past, when central banks like the U.S. Federal Reserve cut
interest rates to low levels, they manage to create economic booms by
encouraging borrowing and higher asset prices. These economic booms are
often based on dangerous economic bubbles that burst and lead to
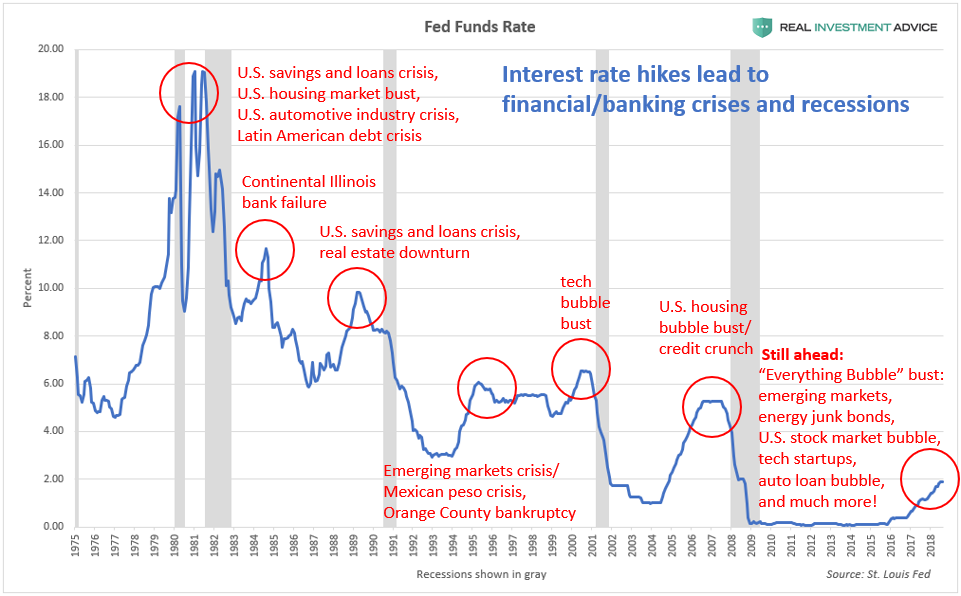
recessions when interest rates are normalized again. As the chart below
shows, financial crises and recessions (see the gray vertical bars)
occur after rate hike cycles, including the dot-com and U.S. housing
market crashes.
The false economic booms that occur when central banks interfere with
the business cycle trick investors and entrepreneurs into thinking that
they are organic and sustainable booms. When the booms inevitably turn
to busts, the bad investments that result are known as malinvestments – 中央銀行が景気サイクルに介入することで生み出される偽の景気ブームは投資家や起業家に誤解を引き起こす、この経済ブームは自然なもので持続的なものだと。ブームというものには必ず終焉がある、このとき、筋悪投資がはじめてmalinvestmentsとして認識されるーー
Malinvestment is a
mistaken investment in wrong lines of production, which inevitably lead
to wasted capital and economic losses, subsequently requiring the
reallocation of resources to more productive uses. “Wrong” in
this sense means incorrect or mistaken from the point of view of the
real long-term needs and demands of the economy, if those needs and
demands were expressed with the correct price signals in the free
market.
Malinvestmentとは wrong lines of production 方針を間違えた生産への誤解による投資だ、これは必ず資本の浪費となり経済的損失を伴う、その後もっと生産的な目的へと資本の再配分が必要となる。ここで言うところの「Wrong」とは長期的視点での実需を見誤ったという意味だ、自由市場ならばこのような需要には正しい(投資、債務)費用が示される。
Random, isolated entrepreneurial miscalculations and
mistaken investments occur in any market (resulting in standard
bankruptcies and business failures) but systematic, simultaneous
and widespread investment mistakes can only occur through
systematically distorted price signals, and these result in depressions
or recessions. Austrians believe systemic malinvestments occur
because of unnecessary and counterproductive intervention in the free
market, distorting price signals and misleading investors and
entrepreneurs.
For Austrians, prices are an essential information
channel through which market participants communicate their demands and
cause resources to be allocated to satisfy those demands appropriately.
If the government or banks distort, confuse or mislead
investors and market participants by not permitting the price mechanism
to work appropriately, unsustainable malinvestment will be the
inevitable result.
Because the current economic cycle has lasted for an unusually long
time due to the actions of central banks, an unprecedented amount of
malinvestment has built up globally that needs to be cleansed in the
coming recession. It’s similar to a night of drinking: the more you
drink and the later you stay out, the worse your hangover is going to
be. Globally speaking, the last decade has been the bender to
end all benders and the coming hangover is going to proportionally
severe.
Amazonで買物をしてContrarianJを応援しよう 記事を紹介しようと訳を入れている間にFOMCが過ぎてしまいタイミングを逸してしまいました、前半は読み飛ばしてください。後半部分に関して、日本では一般会計と特別会計が別れていて政府財政がわかりにくいですが、米国は分離されておらず年金会計がより鮮明になります。$70Tって邦貨でいうと約7000兆円ですからね。 Whistling Past The $70 Trillion Debt Graveyard 07-26-19 Written by Lance Roberts | Jul, 27, 2019 Last week, we discussed the setup for a near-term mean reversion because of the massive extension above the long-term mean. To wit: 先週には、私どもは短期的な平均回帰のし掛けが出来上がっていることを議論した、というのも現在長期的な平均から極端に乖離しているからだ。見てみよう: “There is also just the simple issue that markets are very extended above their long-term trends, as shown in the chart below. A geopolitical event, a shift in expectations, or an acceleration in economic weakness in the U.S. could spark a mean-reverting event which would be quite the norm of what we have seen in recent years.” 「とてもかんたんなことだが、市場は長期的なトレンドからあまりに極端に上方乖離している、それは下のチャートを見れば明らかだ。地政学的出来事、期待値の変化、もしくは米国経済の弱さが加速するなら、平均回帰を引き起こすだろう、それは過去数年でみた典型的な相場の動きだ。」 This analysis is ...
Productivity: What It Is & Why It Matters Written by Michael Lebowitz | Jan, 16, 2019 The Kansas City Federal Reserve posted the Twitter comment and graph below highlighting a very important economic theme. Although productivity is a basic building block of economic analysis, it is one that few economists and even fewer investors seem to appreciate. Kansas 市FEDがツイッターにコメントを投稿した、そのグラフを下に示す、とても重要な経済テーマだ。経済分析においては生産性というのはとても重要な要素だが、ほとんどのエコノミストがこの件に言及しない、投資家は更にこのことを忘れ去っている。 The Kansas City Fed’s tweet is 100% correct in that wages are stagnating in large part due to low productivity growth. As the second chart shows, it is not only wages. The post financial-crisis economic expansion, despite being within months of a record for duration, is by far the weakest since WWII. Kansas City FEDのツイートは100%正しい、給与が停滞している原因の主要因は生産性成長が低いからだ。二番目のチャートを見ても判るように、成長鈍化は給与だけではない。あの金融危機後の経済拡大は、第二次世界大戦後で記録的長期の拡大期間だが、とても弱い拡大だ。 Productivity growth over the last 350+ years is ...
この記事は投資人生を通じて有効です。 The Beginning is the End is the Beginning: A Look at Recessions Market Commentary Stocks By Liz Ann Sonders February 25, 2019 Key Points Recessions are not back-to-back negative GDP quarters; they’re instead defined using four key coincident economic indicators. 景気後退とはマイナスGDP成長四半期が連続することではない;そうではなく4つの重要経済指標で定義される。 Bear markets often overlap with recessions (and typically lead them), but not always. ベア相場は景気後退と重なることが多い(典型的には先行する)、しかし必ずそうというわけでもない。 It’s important to distinguish between leading and lagging economic indicators and to focus at least as much on trend as level. 大切なことは先行指標と遅行指標を見極めること、そしてすくなくともそのトレンドに注意せよ。 Recession chatter is abundant lately. It’s increasingly the focus of Q&A sessions at investor events at which I’ve been speaking. I also received a series of questions last week about recessions fro...
米国はよく理解してませんが、日本の場合では量的緩和で日銀が国債買い上げした資金は日銀当座預金にそのままです、市中には流れていません。でもNHKのニュース等では「ジャブジャブ」という表現をアナウンサーが使い、さらに丁寧に水道の蛇口からお金が吐き出される画像まで示してくれます。これって心理効果が大きいですよね。量的緩和とは何かを7時のニュースや新聞でこれ以上丁寧に解説するのはそう簡単ではありません。一般の人も株式をやっている人も「イメージ」で捉える以上はそう簡単にできません。多くの人は量的緩和とはなにか、を理解していないと私は想像しています。 ただし、国債を買い上げるので長期金利が低下し住宅ローン金利等が下がったのは確実な効果です。一方で長短金利差が少なくなると銀行のビジネスモデルが成り立たなくなりますが。 This Is The One Chart Every Trader Should Have "Taped To Their Screen" by Tyler Durden Sat, 01/19/2019 - 18:55 After a year of tapering, the Fed’s balance sheet finally captured the market’s attention during the last three months of 2018. 一年間のテーパリング後、FEDバランスシートがとうとう市場の注目をあびることになった、2018年の最後の3ヶ月だ。 By the start of the fourth quarter, the Fed had finished raising the caps on monthly roll-off of its balance sheet to the full $50bn per month (peaking at $30bn USTs, $20bn MBS...