After
several unsuccessful attempts to put his preferred candidates on the
Fed's board, moments ago Donald Trump announced that he intends to
nominate Christopher Waller, who is currently the Executive VP and
Director of Research, at the St. Louis Fed, to the board of the Federal
Reserve. Prior to his current position, Christopher served as a
professor and Chair of Economics at Notre Dame.
トランプ大統領は彼のお気に入りを何度かFED取締役に推奨したがうまくゆかなかった、今度はChiristopher Wallerを推薦した、彼は現在セントルイスFEDのEcexutove VPとDirector of Reserch の役にある。現在の仕事の前は、Chrisotperはノートルダム大学の経済学会長兼教授だった。
I am pleased to announce that it is my intention to nominate Christopher Waller, Ph. D., Executive VP and Director of Research, Federal Reserve Bank of St. Louis, Missouri, to be on the board of the Federal Reserve....
He received his B.S. in economics from Bemidji State University in
1981, and his M.A. and Ph.D. from Washington State University in 1984
and 1985, respectively. His principal research interests are monetary
theory, political economy and macroeconomic theory.
1981年にBemidji State University で経済学BSを取得、その後M.A.とPh.DをWashington State Universityで取得、1984,1985。主な研究分野は金融理論、政治経済とマクロ経済理論。
Prior to joining the Fed as research director in June 2009, Mr.
Waller served as a professor and the Gilbert F. Schaefer Chair of
Economics at the University of Notre Dame. He was also a research fellow
with Notre Dame's Kellogg Institute for International Studies.
2009年6月にFEDの研究ディレクターになる前は、Mr. Wallerはノートルダム大学の経済学教授。彼はまたノートルダムKellogg Institute for International Studiewの研究フェローだった。
From 2006 to 2007, he served as the acting department chair for Notre
Dame's Department of Economics and Econometrics. From 1998 to 2003, Mr.
Waller was a professor and the Carol Martin Gatton Chair of
Macroeconomics and Monetary Economics at the University of Kentucky.
During that time, he was also a research fellow at the Center for
European Integration Studies (ZEI) at the University of Bonn. From
1992-1994, he served as the director of graduate studies at Indiana
University's Department of Economics, where he also served as associate
professor (1992 to 1998) and an assistant professor (1985 to 1992).
2006から2007年にはノートルダム大学経済学計量経済学、学部長だった。1998から2003年にはMr. Wallerはケンタッキー大学、Carol Marin Gatton Chair of MacroeconomissあんdMonetary Economicsの教授だった。投じ、かれはまたボン大学Center for European Integration Studiesのフェローリサーチャーだった。1992−1994には、インディアナ大学経済学部大学院のディレクターだった、そこで1992−1998に准教授、そして1985−1992に助教授だった。
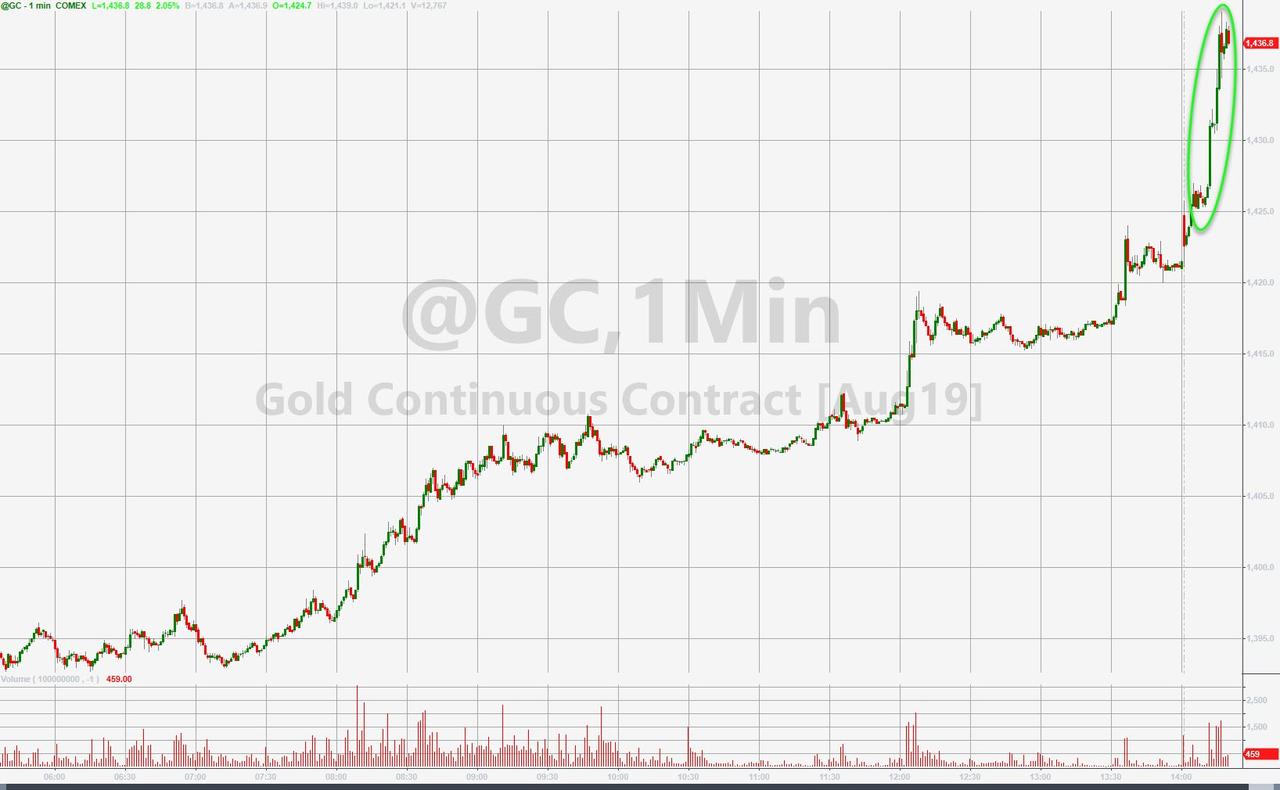
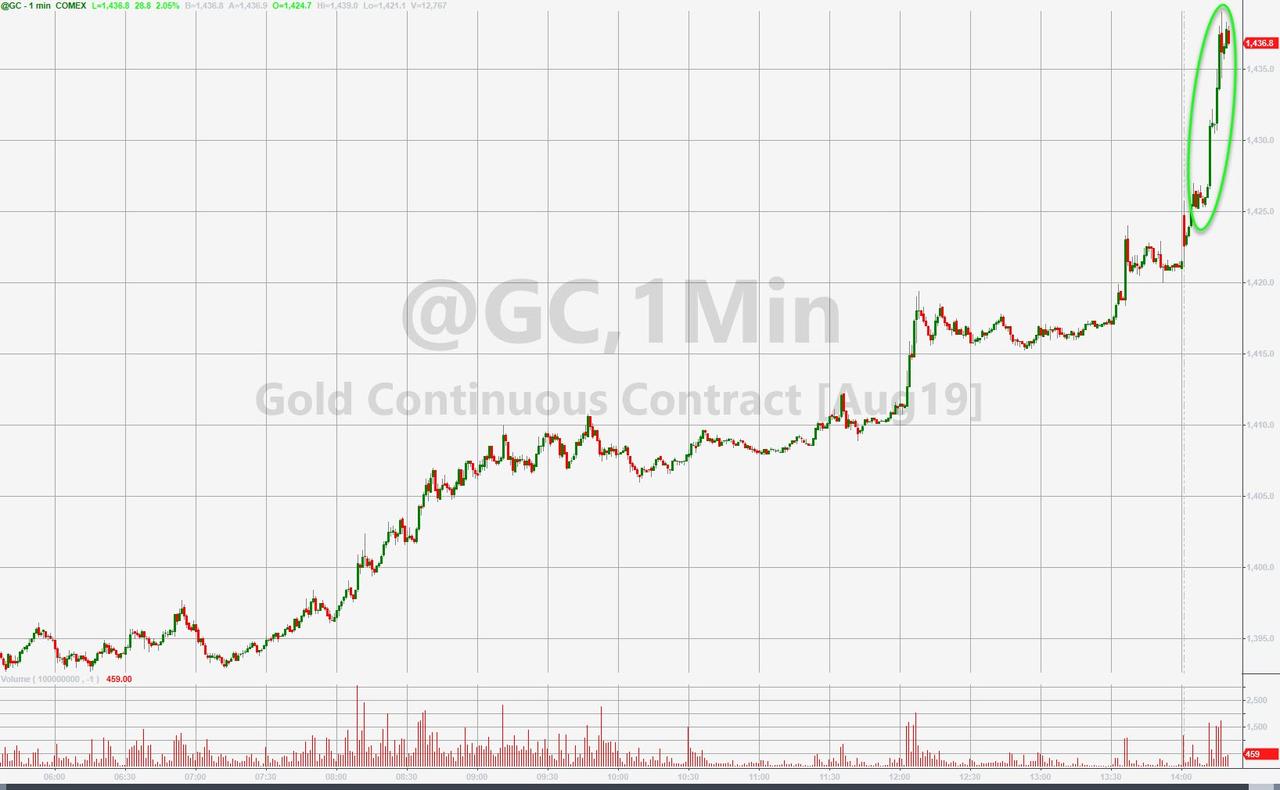
However, the reason why gold is spiking after hours, is that shortly
after tweeting the Waller nomination, Trump also confirmed the
previously rumored nomination of Judy Shelton to the Fed board:
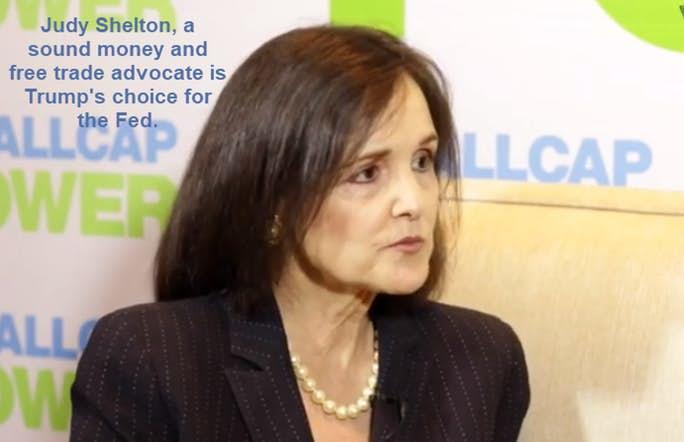
I am pleased to announce that it is my intention to nominate Judy
Shelton, Ph. D., U.S. Executive Dir, European Bank of Reconstruction
& Development to be on the board of the Federal Reserve Judy is a
Founding Member of the board of directors of Empower America and has
served on the board of directors of Hilton Hotels.
ここで謹んでご報告する、私はJudy Shelton Ph.D、Eutopean Bank of Reconstruction & Developmentの米国代表役員、をFED役員に推薦する。JudyはEmpower Americaの創設メンバーで、ヒルトンホテルの取締役でも在る。
I am pleased to announce that it is my intention to nominate Judy Shelton, Ph. D., U.S. Executive Dir, European Bank of Reconstruction & Development to be on the board of the Federal Reserve....
I am pleased to announce that it is my intention to nominate Judy Shelton, Ph. D., U.S. Executive Dir, European Bank of Reconstruction & Development to be on the board of the Federal Reserve....
This is what Bloomberg reported back
in May: "The White House is considering conservative economist Judy
Shelton to fill one of the two vacancies on the Federal Reserve Board of
Governors that President Donald Trump has struggled to fill. She’s
currently U.S. executive director for the European Bank for
Reconstruction and Development, and previously worked for the Sound
Money Project, which was founded to promote awareness about monetary
stability and financial privacy."
5月にブルームバーグはこう報告した:「ホワイトハウスは保守的エコノミストであるJudy SheltonをFEDの役員空席二名の候補と考えている、トランプ大統領はこれを埋めることに積極的だ。彼女は現愛European Bank for Reconstruction and Develompentの米国代表役員で、これまでSound Money Projectで働いていた、この組織は金融安定化と財政プライバシーのために創設されたものだ。」
Since President Trump announced his intention to nominate Herman Cain
and Stephen Moore to serve on the Federal Reserve’s board of governors,
mainstream commentators have made a point of dismissing anyone
sympathetic to a gold standard as crankish or unqualified.
But it is wholly legitimate, and entirely prudent, to
question the infallibility of the Federal Reserve in calibrating the
money supply to the needs of the economy. No other government
institution had more influence over the creation of money and credit in
the lead-up to the devastating 2008 global meltdown. And the Fed’s
response to the meltdown may have exacerbated the damage by lowering the
incentive for banks to fund private-sector growth.
What began as an emergency decision in the wake of the financial
crisis to pay interest to commercial banks on excess reserves has become
the Fed’s main mechanism for conducting monetary policy. To raise
interest rates, the Fed increases the rate it pays banks to keep their
$1.5 trillion in excess reserves—eight times what is required—parked in
accounts at Federal Reserve district banks. Rewarding banks for holding
excess reserves in sterile depository accounts at the Fed rather than
making loans to the public does not help create business or spur job
creation.
Meanwhile, for all the talk of a “rules-based” system for
international trade, there are no rules when it comes to ensuring a
level monetary playing field. The classical gold standard established an
international benchmark for currency values, consistent with free-trade
principles. Today’s arrangements permit governments to manipulate their
currencies to gain an export advantage.
Money is meant to serve as a reliable unit of account and store of value across borders and through time. It’s
entirely reasonable to ask whether this might be better assured by
linking the supply of money and credit to gold or some other reference
point as opposed to relying on the judgment of a dozen or so monetary
officials meeting eight times a year to set interest rates. A
linked system could allow currency convertibility by individuals (as
under a gold standard) or foreign central banks (as under Bretton
Woods). Either way, it could redress inflationary pressures.
マネーとは本来国を超え時間を超えて信頼できる store of value であるはずだ。マネーと与信の供給をゴールドもしくは他の基準に連動させるといのは全く合理的なことで、一方現在は年に8回も各国の金融担当者が会合を持つのとは全く違う手法だ。こういう連動システムは個人の取引(金本位制のもとで)も各国中央銀行間(Bretton Woodsのもとで)の通貨交換をも可能にする。 どちらにしろインフレ圧力を無くする。
Judy Shelton is author of the 1998 book Money Meltdown; and previously she had concluded that "Central bankers, and their defenders, have proven less than omniscient."
コメント欄に詳しい解説が書き込まれています。 英語でいうところの「buy back」と「insider buy」は異なる概念です。日本語の記事でどちらも自社株買いとされていることがあり、これを混同すると意味不明の記事になってしまいます。 The Great Stock Buyback Debate Written by Lance Roberts | May, 2, 2019 I recently wrote about stock buybacks in our weekly newsletter. However, a recent report from Axios noted that for 2019, IT companies are again on pace to spend the most on stock buybacks this year, as the total looks set to pass 2018’s $1.085 trillion record total. 最近私は週間記事で自社株買いに関して議論した。しかしながら、Axiosの最近の2019報告書によると、IT企業は再び今年その規模を増やしている、2018年は$1.085Tと記録的規模だったが、今年はこれを超えそうだ。 “By the numbers: Companies so far have spent $272 billion on buybacks, data compiled by Mike Schoonover, COO of Catalyst Funds, for Axios shows. 「数値を見る限り:企業は$272Bをすでに自社株買いに費やした、数値の解釈はMike Schoonoverによるものだ、彼はCatalyst FundsのCOOだ、Axiosがデータを示す。 Between the lines: The amount of spending on buybacks announced by companies in the IT sector has fallen significantly this year as other i...
米国はよく理解してませんが、日本の場合では量的緩和で日銀が国債買い上げした資金は日銀当座預金にそのままです、市中には流れていません。でもNHKのニュース等では「ジャブジャブ」という表現をアナウンサーが使い、さらに丁寧に水道の蛇口からお金が吐き出される画像まで示してくれます。これって心理効果が大きいですよね。量的緩和とは何かを7時のニュースや新聞でこれ以上丁寧に解説するのはそう簡単ではありません。一般の人も株式をやっている人も「イメージ」で捉える以上はそう簡単にできません。多くの人は量的緩和とはなにか、を理解していないと私は想像しています。 ただし、国債を買い上げるので長期金利が低下し住宅ローン金利等が下がったのは確実な効果です。一方で長短金利差が少なくなると銀行のビジネスモデルが成り立たなくなりますが。 This Is The One Chart Every Trader Should Have "Taped To Their Screen" by Tyler Durden Sat, 01/19/2019 - 18:55 After a year of tapering, the Fed’s balance sheet finally captured the market’s attention during the last three months of 2018. 一年間のテーパリング後、FEDバランスシートがとうとう市場の注目をあびることになった、2018年の最後の3ヶ月だ。 By the start of the fourth quarter, the Fed had finished raising the caps on monthly roll-off of its balance sheet to the full $50bn per month (peaking at $30bn USTs, $20bn MBS...
このブログ左の参考図書の一つがHoward Marksの本です。初めてこの本を読んだ時、管理人は目からウロコが取れた思いでした。 Howard Marks: "We Had One Of The Most Violent Downdrafts I Had Ever Seen" by Tyler Durden Mon, 01/14/2019 - 09:28 Right around the market peaked on September 2018, Oaktree's iconic founder Howard Marks published a letter to investors in which he warned that the market conditions made it "a time for caution", to wit: 市場がピークを迎えた2018年9月ころ、Oaktreeの伝説的創業者 Howard Marksが投資家向けレターを発行した、この中で市場環境は「注意すべき時だ」と警告した、見てみよう: I’m absolutely not saying people shouldn’t invest today, or shouldn’t invest in debt. Oaktree’s mantra recently has been, and continues to be, “move forward, but with caution.” The outlook is not so bad, and asset prices are not so high, that one should be in cash or near-cash. The penalty in terms of likely opportunity cost is just too great to ...
Amazonで買物をしてContrarianJを応援しよう Here Are The Recession Warning Signs To Watch by Tyler Durden Thu, 06/13/2019 - 10:25 Authored by Jesse Colombo via RealInvestmentAdvice.com, Last week, I wrote a detailed piece in which I explained that U.S. recession risk was rising quite rapidly and that the coming recession is likely to be far more severe than most economists expect because there are so many dangerous new bubbles inflating currently and because the global debt burden is much worse today than it was before the Great Recession . In the current piece, I will show more warning signs of the coming recession as well as discuss reliable recession indicators to keep an eye on as we get closer to the recession. 先週のことだ、米国の景気後退リスクが急速に高まっていることを詳細に解説した、そして次の景気後退は多くのエコノミストが予想するよりも遥かに深刻なものになりそうだ、その理由は、現在あまりに多くの新たなバブルが膨れ上がっており、また現在の世界債務負荷はあの金融危...
The US Consumer Just Hit A Brick Wall: Here's Why In 15 Charts by Tyler Durden Tue, 03/05/2019 - 17:05 When it comes to the growth dynamo behind the global economy, nobody can match the US consumer - not even China: accounting for trillions in annual spending, the US consumer, who represents roughly 70% of US GDP, is also responsible for roughly 17% of global GDP, slightly ahead of the entire country of China. 世界経済の成長エンジンを議論する時、米国消費以上のものはないーー中国ではない:年間トリリオンドルを米国消費者は使っている、これが米国GDPの70%、そして世界GDPの17%を占める、中国全GDPよりも大きい。 However, as recent economic data has shown, the future of the US consumer is suddenly looking ominously cloudy, for two big reasons: rising interest rates, which as Deutsche Bank notes are "beginning to bite" as observed in the number of working hours in sector selling big ticket items... しかしながら最近の経済デ...