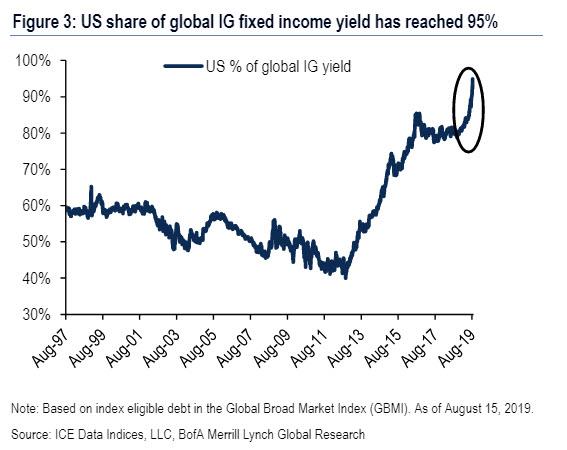
Last
Friday afternoon, when what few traders were not on vacation were
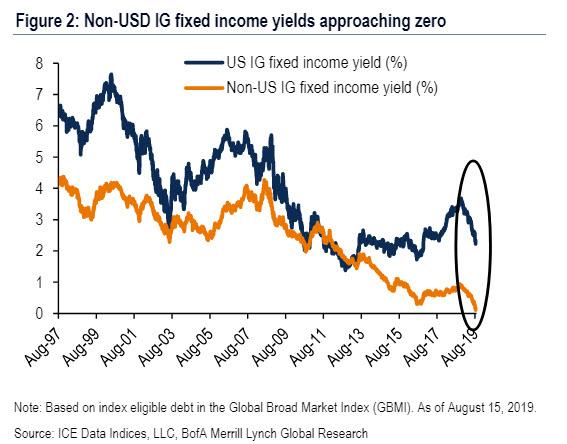
planning the venue of their evening alcohol consumption, we showed a remarkable analysis by Bank of America, which found that yields on the $27.8 trillion non-USD global
investment grade bond market had declined to just 16bps and that the US
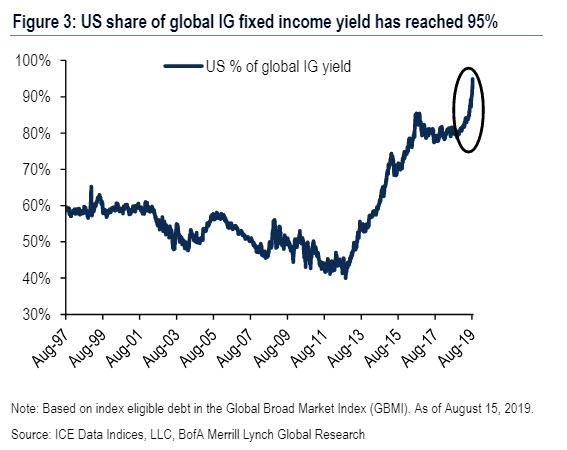
share of global investment grade yields has climbed to 94%. But the
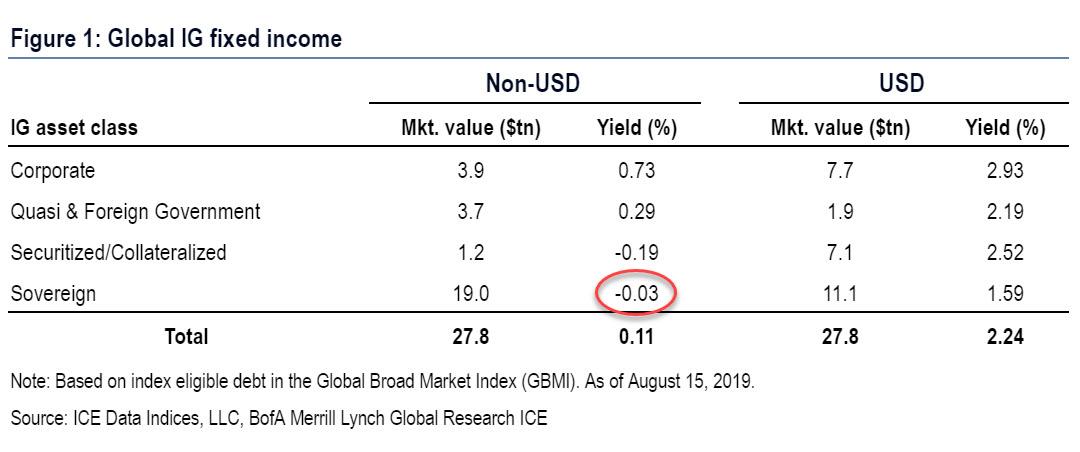
punchline is that, as we said, "non-USD sovereign yields had
dropped to just 2bps, meaning that any day now foreign sovereign debt
may have no yield at all on average."
Fast forward to Monday, when following another surge in global bond
prices, Bank of America refreshed its analysis, and foudn that the
striking trends noted last week had become even more fascinating, to wit
yields on the $27.8tn non-USD global IG fixed income market had
declined to just 11bps (down from 16bps just one day earlier)...
... and the US share of global IG yields climbed to 95%...
... meaning that any foreign investor who is desperate for even the
smallest trace of positive yield has no choice but to come to the US,
something Kyle Bass echoed earlier on CNBC: "US rates are going to zero
because they are the only DM yields with an integer in front of them."
But the biggest shock is that for Albert Edwards, vindication is here
if only outside the US for now: as per the BofA update, non-USD
sovereign yields on $19 trillion in global debt - which was a paltry but
positive +0.02% on Friday - have now turned negative on average for the
first time ever at -3bps.
The silver lining: for now the average US sovereign yield is like a
beacon for foreign investors, offering a "juicy" 1.59% but we fully
expect this number to keep dropping as offshore pension funds rush to
lock in positive yields while they can; naturally any further Fed rate
cuts or "some QE" will only bring the US D-Day that much closer.
It's not just us: commenting on the Japanification of the world, Bank
of America's Hans Mikkelsen wrote that "we continue to think there is a
wall of new money being forced into the global corporate bond market"
and adds that "the trigger is lower interest rate volatility or simply
the passage of time, as a lot of foreign investors are being charged
(negative yields) for being underinvested."
Amazonで買物をしてContrarianJを応援しよう この長文記事をRay Dalioが発表し、ゴールドは$1400から$1420へと急騰しました。GLD保持高に変化はないのでたぶん先物ポジションが進んでいます。 Ray Dalio Warns A "New Paradigm" Is Coming: "Buy Gold, Sell Stocks" by Tyler Durden Wed, 07/17/2019 - 14:44 Authored by Ray Dalio via LinkedIn, One of my investment principles is: 私の投資原則はこういうものだ: Identify the paradigm you’re in, examine if and how it is unsustainable, and visualize how the paradigm shift will transpire when that which is unsustainable stops. 現在のパラダイムを認識し、それがどの程度持続可能かどうか判断する、そしてパラダイムシフトがどのように起きるか、そしてその着地点を思い描く。 Over my roughly 50 years of being a global macro investor, I have observed there to be relatively long of periods (about 10 years) in which the markets and market relationships operate in a certain way (which I call “paradig...
Amazonで買物をしてContrarianJを応援しよう 記事を紹介しようと訳を入れている間にFOMCが過ぎてしまいタイミングを逸してしまいました、前半は読み飛ばしてください。後半部分に関して、日本では一般会計と特別会計が別れていて政府財政がわかりにくいですが、米国は分離されておらず年金会計がより鮮明になります。$70Tって邦貨でいうと約7000兆円ですからね。 Whistling Past The $70 Trillion Debt Graveyard 07-26-19 Written by Lance Roberts | Jul, 27, 2019 Last week, we discussed the setup for a near-term mean reversion because of the massive extension above the long-term mean. To wit: 先週には、私どもは短期的な平均回帰のし掛けが出来上がっていることを議論した、というのも現在長期的な平均から極端に乖離しているからだ。見てみよう: “There is also just the simple issue that markets are very extended above their long-term trends, as shown in the chart below. A geopolitical event, a shift in expectations, or an acceleration in economic weakness in the U.S. could spark a mean-reverting event which would be quite the norm of what we have seen in recent years.” 「とてもかんたんなことだが、市場は長期的なトレンドからあまりに極端に上方乖離している、それは下のチャートを見れば明らかだ。地政学的出来事、期待値の変化、もしくは米国経済の弱さが加速するなら、平均回帰を引き起こすだろう、それは過去数年でみた典型的な相場の動きだ。」 This analysis is ...
米国はよく理解してませんが、日本の場合では量的緩和で日銀が国債買い上げした資金は日銀当座預金にそのままです、市中には流れていません。でもNHKのニュース等では「ジャブジャブ」という表現をアナウンサーが使い、さらに丁寧に水道の蛇口からお金が吐き出される画像まで示してくれます。これって心理効果が大きいですよね。量的緩和とは何かを7時のニュースや新聞でこれ以上丁寧に解説するのはそう簡単ではありません。一般の人も株式をやっている人も「イメージ」で捉える以上はそう簡単にできません。多くの人は量的緩和とはなにか、を理解していないと私は想像しています。 ただし、国債を買い上げるので長期金利が低下し住宅ローン金利等が下がったのは確実な効果です。一方で長短金利差が少なくなると銀行のビジネスモデルが成り立たなくなりますが。 This Is The One Chart Every Trader Should Have "Taped To Their Screen" by Tyler Durden Sat, 01/19/2019 - 18:55 After a year of tapering, the Fed’s balance sheet finally captured the market’s attention during the last three months of 2018. 一年間のテーパリング後、FEDバランスシートがとうとう市場の注目をあびることになった、2018年の最後の3ヶ月だ。 By the start of the fourth quarter, the Fed had finished raising the caps on monthly roll-off of its balance sheet to the full $50bn per month (peaking at $30bn USTs, $20bn MBS...
Mish: Gold Hits New Record High And There's More To Come by Tyler Durden Mon, 07/27/2020 - 10:10 Twitter Facebook Reddit Email Print Authored by Mike Shedlock via MishTalk, Gold futures just touched $1928 taking out the Intraday high of $1923.70 in 2011. ゴールド先物が$1928になり、2011年の日中高値$1923.70を超えた。 11-Week Run 11週連続上昇 Gold is on a huge 11-week run. The last time gold did that was at the 2011 high. ゴールドはなんと11週連続で上昇だ。前回の新高値は2011年のことだった。 Is a pullback in order? A Gold COT chart says otherwise. 通常の引き戻しが待ち構えているだろうか? ゴールドのCoTチャートを見るとそうでもなさそうだ。 Gold COT Chart ゴールドCoTチャート Understanding Futures 先物市場を読み解く In the futures world there is a short for every long. 先物市場ではどのロングにもショートが対応している。 The first horizontal box has Large Specs, Small Specs, and Commercials. This is It's Old COT reporting. この図の下部、最初の横長い箱に示すのは Large Specs、Small Specs、そしてCommercialsのポジションだ。このチャートは従来からのCoT...