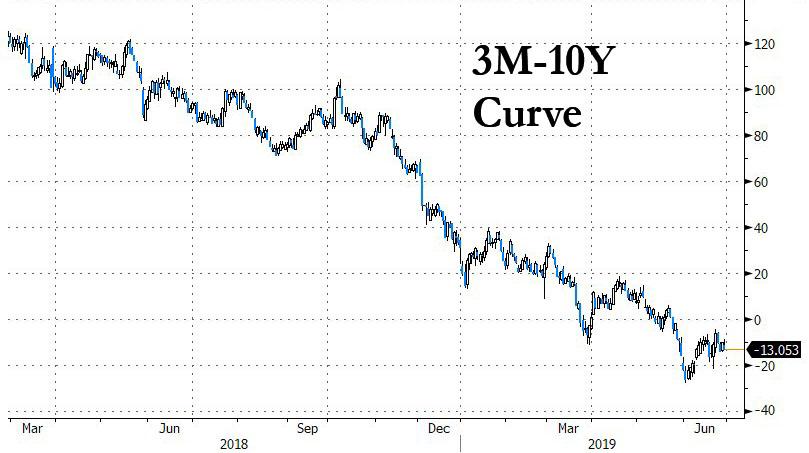
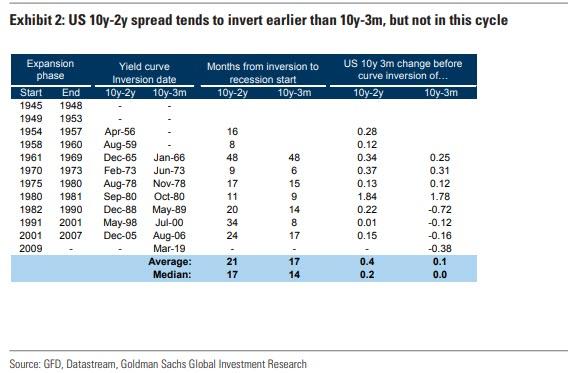
Exactly three months ago, in late March, the 3 month-10 year spread inverted for the first time since 2007...
ちょうど3か月前の3月遅くのことだ、3M10Yスプレッドが2007年以来初めて反転した・・・・
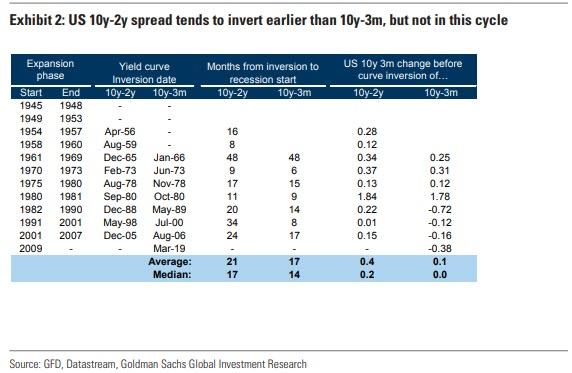
... an event which sparked near-panic in the market as historically curve inversion has preceded the last 7 recessions.
However, while the inversion was certainly a memorable event, the
question on everyone's lips is how do risk assets perform once the curve
flattens and/or inverts. According to backtests from Goldman, since the
mid-1980s, significant stock drawdowns (i.e. market crashes) began only when term slope started steepening after being inverted. しかしながら、イールドカーブ反転は確かに象徴的なできごとだが、誰もが知りたいのはイールドカーブ平坦化・反転化後の株式のパフォーマンスだ。ゴールドマンのバックテストによると、1980年代なかば以来でみて、株価急落が起きるのはイールドカーブ反転後再度急峻になるときだ。
In other words, as we noted then, "Curve Inversion Is Bad, But It's The Steepening After That Kills."
Fast forward to today, when in his latest bearish missive, SocGen's
permabear Albert Edwards picks up where we left off, and in a note
titled "the final recession shoe has now fallen", he notes that while
inversion of the US yield curve is seen as a reliable precursor to US
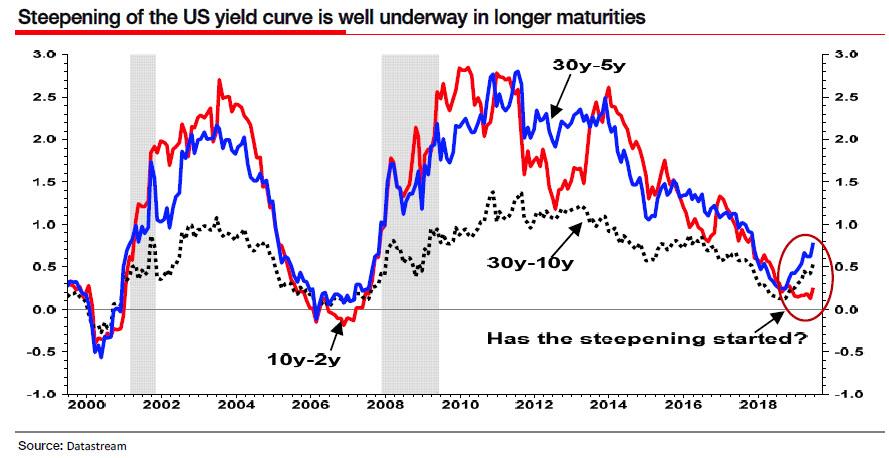
recessions, "it has a long and variable lead time", and instead "a far more immediate and present danger of recession occurs when after inversion, a rapid steepening occurs." 現在までの状況を早送りしてみると、彼の最新の弱気記事だが、SocGenのパーマベア Albert Edwardsがこの話題を取り上げた、ただしZeroHedgeは紹介しなかった、タイトルは「景気後退劇場の最後の見せ場到来」、彼が言うには、米国イールドカーブ反転は信頼できる景気後退予兆だが、「十分なリードタイムがある」、そしてむしろ「インバージョン後に急速に急峻化が起きると、それは直ちに景気後退の危機が迫っている」。
Sound familiar?
知ってました?
In any case, as we first commented in early 2019, Edwards notes that this subsequent steepening "usually informs investors the cycle is over and it is time to flee for the hills."
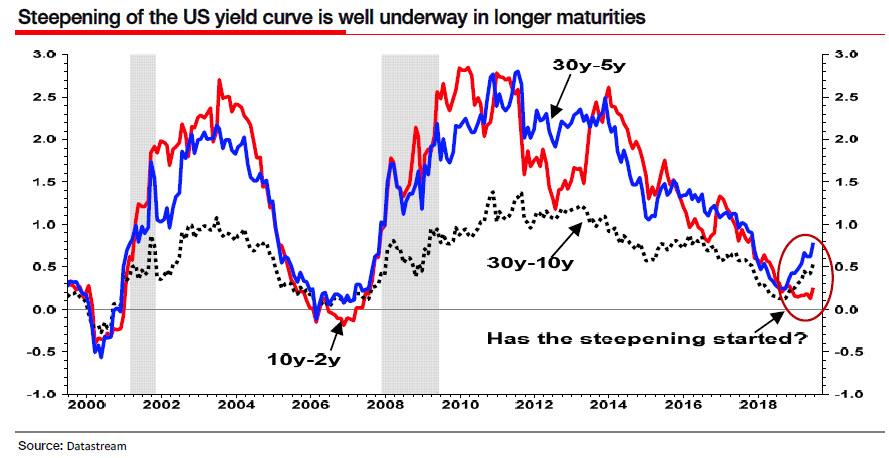
Well, for those who haven't figured out the punchline yet, rapid curve steepening is now occurring, and as Edwards gleefully concludes, this "suggests recession may indeed either be imminent or else it has already arrived." そう、まだ結末を認識できない人に教えてあげよう、急速なイールドカーブ急峻化がいま起きつつ在る、そしてEdwardsが明快に結論付けるが、この状況は「景気後退がすぐそこに差し迫っている、もしくすでに景気後退入りしている」のだ。
Should Edwards be right, the implications are clearly huge, and not
just for the economy and markets - perhaps the most dramatic consequence
will be what happens with the world's most powerful institution: the
Federal Reserve.
Edwardsの言っていることは正しいのだろうか?、その影響力はあまりに大きい、そして単に経済や市場だけでなくーーたぶんもっとも劇的な結末とは世界最強の組織に起きることだ:the Federal Reserve 。
"As a long time harsh critic of the Fed (and other central banks) for
their obscenely easy money policies" Edwards writes that he is loath to
criticize President Trump’s nearly constant slams of Fed Chair Powell,
especially since President Trump has a very clear agenda: namely, he
is going to make sure the Fed gets the blame from the electorate if the
economy goes into recession and the equity market plunges ahead of the
next presidential election. 「長年FEDや世界の中央銀行には手厳しい批判がなされてきた、緩和政策に浸りすぎてきたことだ」。Edwardsはトランプ大統領を批判したくない、大統領はいつもFED議長Powellを罵る、特にトランプ大統領の意図は明確だ:すなわち、FEDが大統領選挙に責任を負っている、もし景気後退入りとな来年の大統領選挙に向けて株価が下がるとそれはFEDの責任だと。
"And by hook or by crook, Powell will be out on his ear", Edwards says.
「そしてどういう手段を撮ろうとも、Powellは聞く耳を持たないだろう」とEdwardsは言う。
Which is good news and bad news, because while Powell clearly threw
in the towel on the hawkish monster that he was perceived as less than a
year ago when he spooked markets that the Fed would keep hiking until
the mid-3's, and is now as dovish and meek as Yellen or even Bernanke,
it's not like his departure would also end the Fed.
Quite the opposite, because considering that this is what President
Trump is like now, imagine what he will be if the US leads the global
economy into another deep recession and financial crisis like 2008:
Even before the irascible Trump became President, I said the Fed
would lose its (supposed) independence if they were the midwife to
another crisis. There will be no deft, disingenuous shifting of blame to
the commercial banks this time around. The Fed will carry the can.
As a result, Trump will promptly appoint a Fed chair who is the most
dovish one can find, and here Kashkari comes to mind: after all, the
former Goldman IT banker and "architect" of the 2008 bank bailout plan
(or rather Paulson's smokescreen) not accidentally said he was hoping
for a 50bps rate cut earlier this week - he is clearly angling for
Powell's job.
Meanwhile, and going back to the recession narrative, it's not just
the re-steepening of the 3M-10Y. As Edwards ominously concludes, there
is another key indicator that everyone is focused on: "we (and others),
have also pointed out that the alarm bells for an imminent recession
would really start ringing if the 10y-2y curve began to steepen." To be
sure, it is reassuring that this has not happenied - yet - but, as
Edwards concludes "the rest of the yield curve (which leads to 10y-2y
steepening) is now shouting recession from the rooftops."
So how long until Neel "the Chump"
Kashkari is Fed chair? The good news is that it will probably not
happen tomorrow, so readers at least have enough time to buy some more
gold and cryptos before the new Fed chair unleashes the biggest - and
last - liquidity tsunami in US history, one which culminates with the
dollar losing it reserve currency status. Whether that leaves Zuckerberg as the world's central bank, or the IMF finally digitizes the SDR in Libra's footsteps, remains to be seen.
というわけで Neel "the Chump" Kashkari がFED議長になるまでどれくらいの時間が残されているだろうか?幸いなことにそれが明日起きるわけではない、というわけで読者諸君にはまだゴールドや暗号通貨を買います十分な時間が残されている、新任FED議長が米国史上最大で最後の流動性津波を引き起こす前にだ、こうなるとついにドルは準備通貨の地位を失う。こうなるとZuckerbergが世界の中央銀行となるか、もしくはIMFがとうとうLibraの足元でSDRをデジタル化するかもしれない、これを見ることになるかもしれない。
Amazonで買物をしてContrarianJを応援しよう 記事を紹介しようと訳を入れている間にFOMCが過ぎてしまいタイミングを逸してしまいました、前半は読み飛ばしてください。後半部分に関して、日本では一般会計と特別会計が別れていて政府財政がわかりにくいですが、米国は分離されておらず年金会計がより鮮明になります。$70Tって邦貨でいうと約7000兆円ですからね。 Whistling Past The $70 Trillion Debt Graveyard 07-26-19 Written by Lance Roberts | Jul, 27, 2019 Last week, we discussed the setup for a near-term mean reversion because of the massive extension above the long-term mean. To wit: 先週には、私どもは短期的な平均回帰のし掛けが出来上がっていることを議論した、というのも現在長期的な平均から極端に乖離しているからだ。見てみよう: “There is also just the simple issue that markets are very extended above their long-term trends, as shown in the chart below. A geopolitical event, a shift in expectations, or an acceleration in economic weakness in the U.S. could spark a mean-reverting event which would be quite the norm of what we have seen in recent years.” 「とてもかんたんなことだが、市場は長期的なトレンドからあまりに極端に上方乖離している、それは下のチャートを見れば明らかだ。地政学的出来事、期待値の変化、もしくは米国経済の弱さが加速するなら、平均回帰を引き起こすだろう、それは過去数年でみた典型的な相場の動きだ。」 This analysis is ...
米国はよく理解してませんが、日本の場合では量的緩和で日銀が国債買い上げした資金は日銀当座預金にそのままです、市中には流れていません。でもNHKのニュース等では「ジャブジャブ」という表現をアナウンサーが使い、さらに丁寧に水道の蛇口からお金が吐き出される画像まで示してくれます。これって心理効果が大きいですよね。量的緩和とは何かを7時のニュースや新聞でこれ以上丁寧に解説するのはそう簡単ではありません。一般の人も株式をやっている人も「イメージ」で捉える以上はそう簡単にできません。多くの人は量的緩和とはなにか、を理解していないと私は想像しています。 ただし、国債を買い上げるので長期金利が低下し住宅ローン金利等が下がったのは確実な効果です。一方で長短金利差が少なくなると銀行のビジネスモデルが成り立たなくなりますが。 This Is The One Chart Every Trader Should Have "Taped To Their Screen" by Tyler Durden Sat, 01/19/2019 - 18:55 After a year of tapering, the Fed’s balance sheet finally captured the market’s attention during the last three months of 2018. 一年間のテーパリング後、FEDバランスシートがとうとう市場の注目をあびることになった、2018年の最後の3ヶ月だ。 By the start of the fourth quarter, the Fed had finished raising the caps on monthly roll-off of its balance sheet to the full $50bn per month (peaking at $30bn USTs, $20bn MBS...
Productivity: What It Is & Why It Matters Written by Michael Lebowitz | Jan, 16, 2019 The Kansas City Federal Reserve posted the Twitter comment and graph below highlighting a very important economic theme. Although productivity is a basic building block of economic analysis, it is one that few economists and even fewer investors seem to appreciate. Kansas 市FEDがツイッターにコメントを投稿した、そのグラフを下に示す、とても重要な経済テーマだ。経済分析においては生産性というのはとても重要な要素だが、ほとんどのエコノミストがこの件に言及しない、投資家は更にこのことを忘れ去っている。 The Kansas City Fed’s tweet is 100% correct in that wages are stagnating in large part due to low productivity growth. As the second chart shows, it is not only wages. The post financial-crisis economic expansion, despite being within months of a record for duration, is by far the weakest since WWII. Kansas City FEDのツイートは100%正しい、給与が停滞している原因の主要因は生産性成長が低いからだ。二番目のチャートを見ても判るように、成長鈍化は給与だけではない。あの金融危機後の経済拡大は、第二次世界大戦後で記録的長期の拡大期間だが、とても弱い拡大だ。 Productivity growth over the last 350+ years is ...
この記事は投資人生を通じて有効です。 The Beginning is the End is the Beginning: A Look at Recessions Market Commentary Stocks By Liz Ann Sonders February 25, 2019 Key Points Recessions are not back-to-back negative GDP quarters; they’re instead defined using four key coincident economic indicators. 景気後退とはマイナスGDP成長四半期が連続することではない;そうではなく4つの重要経済指標で定義される。 Bear markets often overlap with recessions (and typically lead them), but not always. ベア相場は景気後退と重なることが多い(典型的には先行する)、しかし必ずそうというわけでもない。 It’s important to distinguish between leading and lagging economic indicators and to focus at least as much on trend as level. 大切なことは先行指標と遅行指標を見極めること、そしてすくなくともそのトレンドに注意せよ。 Recession chatter is abundant lately. It’s increasingly the focus of Q&A sessions at investor events at which I’ve been speaking. I also received a series of questions last week about recessions fro...