Many
have wondered if the Fed is ignorant to the problems their policy
prescriptions cause, or if they've just resigned to walking society down
the path to destruction knowingly. It increasingly looks like the
latter. Indeed, the Fed may very well understand that its "lower for
longer" policy is leading the economy and global markets straight into
disaster. However, as the same time, the central bank - feeling trapped
after 10 years of unprecedented stimulus which if undone would result in
a historic crash - is backed into a corner and has no choice but to
accept this growing risk, as the world's punch drunk central bankers
continue to try at all costs to keep the bloated economic "expansion"
going.
Indeed, the Fed itself acknowledges this risk, because according to
the minutes of the FOMC policymaking meeting from March 19 and March 20.
"A few participants observed that the appropriate path for policy,
insofar as it implied lower interest rates for longer periods of time, could lead to greater financial stability risks" the minutes read.
Chairman Powell himself understands very well the risks that he is taking: he has previously pointed out publicly that the last two "expansions" ended in the dot com bubble burst and then the housing bubble burst, according to Bloomberg.
But it is the Fed's willingness to continue down this path, despite
seeing the dangers, that is disturbing. It’s a classic example of
putting a Band-Aid on the problem now at the cost of the future. Holding
rates down while pursuing maximum employment and 2% inflation is a
policy that has proven to lead to disaster.
Tobias Adrian, a senior International Monetary Fund official said: "Easy financial conditions today are good news for downside risks in the short-term but they’re bad news in the medium term."
元IMF職員Tobias Adrianはこう言った:「現在の緩和的金融条件は短期的な相場下落対策には望ましいが、中期的には悪い結末を招く。」
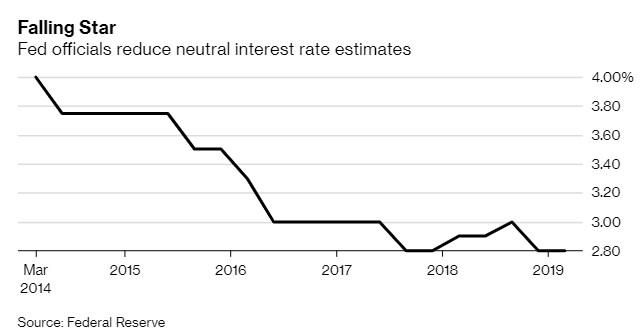
The Fed's dilemma - obvious to everyone but them - is that the neutral rate of interest (i.e. "r star") is simply too low - something we discussed back in 2015 -
so low that, in fact, that instead of keeping the economy at an
equilibrium, it simply encourages more risky behavior by investors.
FEDはジレンマに陥っているーー彼ら以外の誰にも明らかなことだーー中立金利(r star )が低すぎるーーZeroHedgeが2015年に議論したことだがーーこれがここまで低いと経済を均衡維持するだけではなく、投資家がよりリスクを取りやすくなっている。
The neutral rate has continued to fall as a result of rising debt, an
aging population and slower productivity growth. Bloomberg has been using a term
called "FAST-star" instead of "R-star" to denote a rate level that
ensures financial stability. A setting above it stifles risk-taking
while the setting below it encourages excess. The Fed's neutral rate -
"R-star" - falls well below this suggested rate.
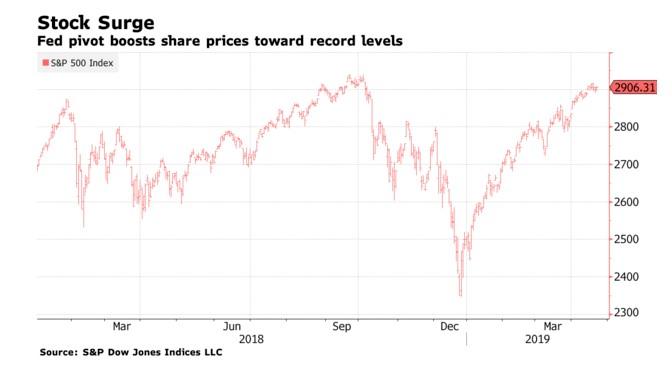
The dovish shift by the Fed at the end of the year last year helped
prompt a massive stock market rally, even after raising rates from 2.25%
to 2.5%. So far the S&P 500 index is up 16% in 2019. However, the
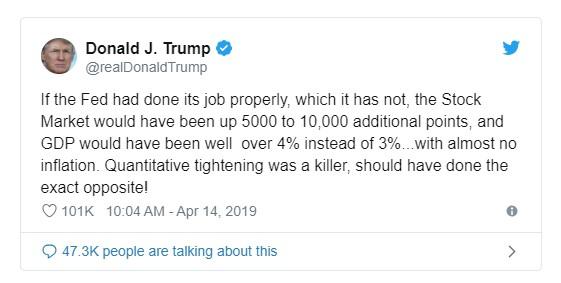
one beating the drum the most in favor of dovish policy – President
Donald Trump – continues to complain that rate increases have held back the economy. 昨年暮れのFEDのハト派姿勢転換は巨額の株式ラリーを引き起こした、たとえ金利を2.25%から2.5%に引き上げた後でもラリーとなった。2019年にはS&P500は16%も上昇した。しかしながら、ハト派政策転換を鐘太鼓でもてはやすのはーー他ならぬDonald Trump大統領だーー彼はいまでも金利引き上げが景気後退を引き起こすと愚痴を言う。
Yet some policymakers at last month's FOMC meeting believe that risks
can be offset by, drumroll, "counter-cyclical macro prudential policy
tools, combined with regulatory and supervisory measures." This is the
same tool and measures that failed to spot the last two financial crises
until both were well underway.
Additionally, there is another problem
to this thinking: even in a best case scenario, the Fed has a limited
set of tools. This was even acknowledged by Fed Vice Chairman for
Supervision Randal Quarles during a March 29 speech.
Meanwhile, Powell has said that he doesn't see a high risk of
financial instability at this point, a comment that may soon be proven
to be as accurate as Ben Bernanke's assertion that "subprime was
contained" prior to the housing crisis. Powell instead argues that the
Fed tries to keep the system safe by requiring large banks to hold
excess capital and undergo stress tests.
And at some points, Fed presidents have sounded open to the idea of
using higher interest rates to cull the markets a little bit. For
instance, New York Fed President John Williams said in October "that the
central bank’s rate increases would help reduce risk-taking in
financial markets, though he added that was not their principal
purpose."
かつてはときに応じて、FED議長によっては、市場の行き過ぎを抑制するために高金利とすると公言していた。たとえば、New York FED議長 John Williamsの10月の発言はこうだ、「中央銀行が金利を引き上げることで金融市場での過剰なリスクテイクを抑圧するだろう」、ただしそれが一義的な目的ではないということも付け加えた。
But that type of talk has faded since then.
しかしそれ以降こういう発言は消え失せた。
Jonathan Wright, a professor at Johns Hopkins University and a former
Fed economist said: "There doesn’t seem to be the same idea of having
tighter monetary policy so as to lessen the risk of asset bubbles
developing."
In April former Treasury Secretary Lawrence Summers concluded: "There
are reasons for fearing the economic consequences of very low
rates. These include a greater propensity to asset bubbles and
incentives to substantially increase leverage."
Ultimately, the Fed indeed has no choice: either it inflates away the
debt - which is where MMT will come in very handy in a few years as
helicopter money is unleashed under the guise of "QE for the people" -
or it's game over for the status quo anyway. If it means creating the
biggest asset bubble in the process, so be it.
米国はよく理解してませんが、日本の場合では量的緩和で日銀が国債買い上げした資金は日銀当座預金にそのままです、市中には流れていません。でもNHKのニュース等では「ジャブジャブ」という表現をアナウンサーが使い、さらに丁寧に水道の蛇口からお金が吐き出される画像まで示してくれます。これって心理効果が大きいですよね。量的緩和とは何かを7時のニュースや新聞でこれ以上丁寧に解説するのはそう簡単ではありません。一般の人も株式をやっている人も「イメージ」で捉える以上はそう簡単にできません。多くの人は量的緩和とはなにか、を理解していないと私は想像しています。 ただし、国債を買い上げるので長期金利が低下し住宅ローン金利等が下がったのは確実な効果です。一方で長短金利差が少なくなると銀行のビジネスモデルが成り立たなくなりますが。 This Is The One Chart Every Trader Should Have "Taped To Their Screen" by Tyler Durden Sat, 01/19/2019 - 18:55 After a year of tapering, the Fed’s balance sheet finally captured the market’s attention during the last three months of 2018. 一年間のテーパリング後、FEDバランスシートがとうとう市場の注目をあびることになった、2018年の最後の3ヶ月だ。 By the start of the fourth quarter, the Fed had finished raising the caps on monthly roll-off of its balance sheet to the full $50bn per month (peaking at $30bn USTs, $20bn MBS...
コメント欄に詳しい解説が書き込まれています。 英語でいうところの「buy back」と「insider buy」は異なる概念です。日本語の記事でどちらも自社株買いとされていることがあり、これを混同すると意味不明の記事になってしまいます。 The Great Stock Buyback Debate Written by Lance Roberts | May, 2, 2019 I recently wrote about stock buybacks in our weekly newsletter. However, a recent report from Axios noted that for 2019, IT companies are again on pace to spend the most on stock buybacks this year, as the total looks set to pass 2018’s $1.085 trillion record total. 最近私は週間記事で自社株買いに関して議論した。しかしながら、Axiosの最近の2019報告書によると、IT企業は再び今年その規模を増やしている、2018年は$1.085Tと記録的規模だったが、今年はこれを超えそうだ。 “By the numbers: Companies so far have spent $272 billion on buybacks, data compiled by Mike Schoonover, COO of Catalyst Funds, for Axios shows. 「数値を見る限り:企業は$272Bをすでに自社株買いに費やした、数値の解釈はMike Schoonoverによるものだ、彼はCatalyst FundsのCOOだ、Axiosがデータを示す。 Between the lines: The amount of spending on buybacks announced by companies in the IT sector has fallen significantly this year as other i...
このブログ左の参考図書の一つがHoward Marksの本です。初めてこの本を読んだ時、管理人は目からウロコが取れた思いでした。 Howard Marks: "We Had One Of The Most Violent Downdrafts I Had Ever Seen" by Tyler Durden Mon, 01/14/2019 - 09:28 Right around the market peaked on September 2018, Oaktree's iconic founder Howard Marks published a letter to investors in which he warned that the market conditions made it "a time for caution", to wit: 市場がピークを迎えた2018年9月ころ、Oaktreeの伝説的創業者 Howard Marksが投資家向けレターを発行した、この中で市場環境は「注意すべき時だ」と警告した、見てみよう: I’m absolutely not saying people shouldn’t invest today, or shouldn’t invest in debt. Oaktree’s mantra recently has been, and continues to be, “move forward, but with caution.” The outlook is not so bad, and asset prices are not so high, that one should be in cash or near-cash. The penalty in terms of likely opportunity cost is just too great to ...
コメント欄に詳しい解説が書き込まれています。ぜひ、一読を。 When The S&P Hit A Record High, The Only Buyer Was Buybacks; Everyone Else Was Selling by Tyler Durden Tue, 05/07/2019 - 14:26 Bloomberg's Michael Regan has taken a lot of heat for his Friday article " The U.S. Stock Market Can’t Stop, Won’t Stop Its Endless Rally " , which prompted some to ask if Bloomberg, with its "millennialized", click-optimized newsroom, has become the new Barron's. ブルームバーグのMichael Regan が金曜の記事で熱く語った「米国株式市場は止まることはない、止まること無きエンドレスラリーだ」、この記事を見てブルームバーグが変貌したのではないかと思う人もいた、「千年王国的か」、アクセス獲得の見せかけHPに変わったか、新手のバロン誌に変貌したか、という具合だ。 And yet, Regan's less than prescient headline notwithstanding, he made an accurate point in his teaser, namely that " regular investors are leaving. " That, as we have pounded the table week after week after week, has been ...